
Insights
HVAC Working Capital vs Customer Financing
Half the results for 'HVAC financing' are customer loans, not business capital. What each product does, what it costs, and which one your company needs.
The short answer
"HVAC financing" names two different products. Customer financing lets a homeowner pay for a new system over time — a sales tool that closes high-ticket replacements. Working capital is money your business borrows to stock equipment, carry payroll, and fund the pre-season push. One raises close rates; the other keeps the operation running. Most growing HVAC companies eventually use both.
Key takeaways
- Customer financing is your customer's loan; working capital is your company's. The two are not interchangeable.
- Dealer fees make customer financing a margin decision — and heavier financed volume is itself a working-capital consideration.
- A declared seasonal trough is underwritten as context; unexplained volatility is priced as risk.
- The pre-season window — stock, hires, marketing before the first heat wave — is where HVAC working capital earns its keep.
- If replacements are dying on price at the kitchen table, business capital will not fix a close-rate problem.
Search "HVAC financing" and the first page is answering two different questions at once. Half the results are platforms that help your customers pay for a new system over time. The other half — the smaller half — is working capital for the business doing the installing. The words are nearly identical. The products have almost nothing in common.
We fund HVAC and home-services companies, so we sit on one side of that divide — but the confusion costs owners real time and occasionally real money, so it is worth taking apart properly. Here is what each product actually is, what each one costs, and how to tell which problem you are holding.
Two products are wearing the same name
Customer financing — also sold as consumer financing, point-of-sale financing, or dealer financing — is a loan your customer takes out to pay for their new system. A third-party lender reviews the homeowner at the kitchen table, you get paid the invoice up front minus a dealer fee, and the platform owns the repayment relationship from there. Its job is singular: it closes high-ticket replacements that would otherwise die on price.
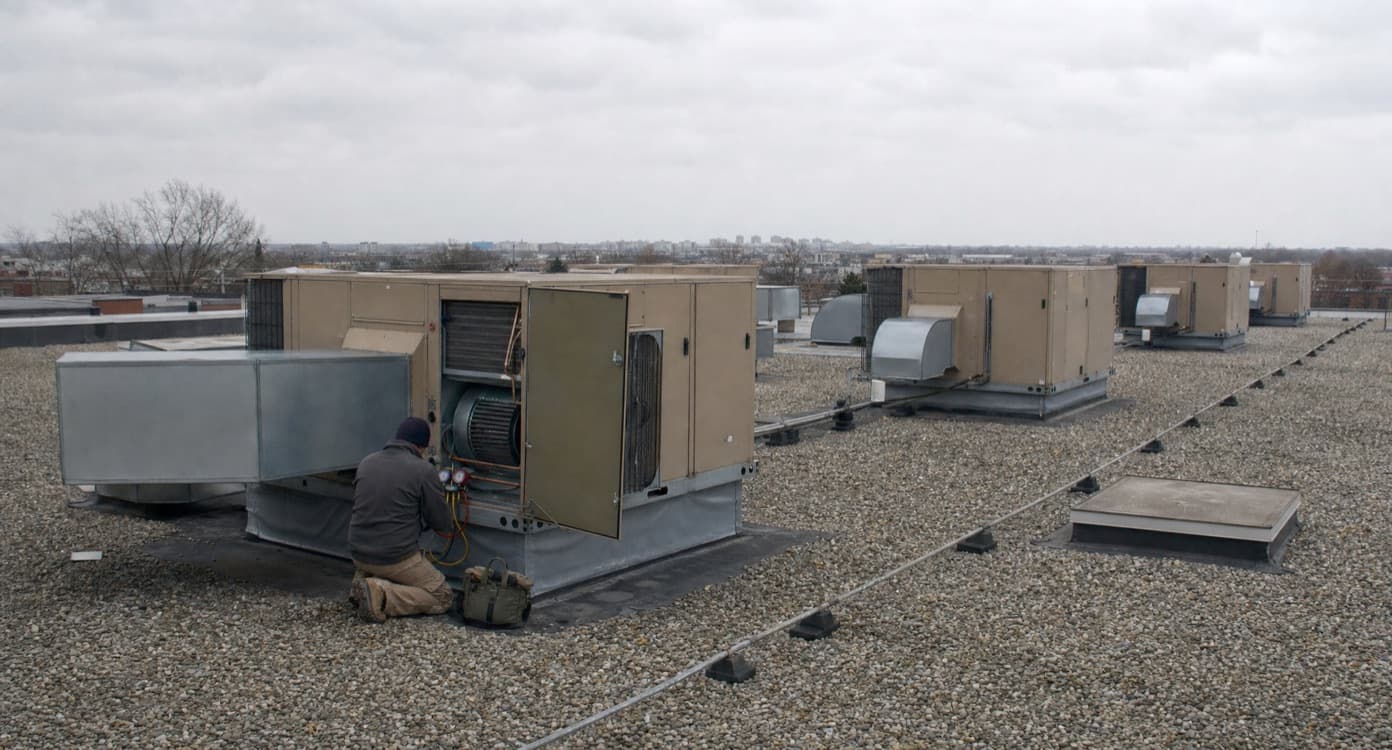
Working capital is money your business borrows. It stocks condensers in April, carries payroll through the shoulder months, books marketing before the first heat wave, and fixes the van that earns the revenue. Your company's deposits are what get reviewed, your company repays it, and your customer never knows it exists.
| Customer financing | Revenue-based working capital | |
|---|---|---|
| Who borrows | Your customer, the homeowner | Your company |
| Whose file is reviewed | The homeowner's credit | Your deposits, their consistency, and your time in business |
| What it solves | Sticker shock on high-ticket replacements | Cash-flow timing: pre-season stock, payroll, marketing, repairs |
| How you pay for it | A dealer fee deducted from each funded invoice | A fixed cost agreed before you sign |
| What it cannot do | Run your operation | Raise your close rate |
Customer financing is a sales tool that leans on your margin
The platforms are not wrong about what they do: offering a monthly payment on a replacement quote genuinely raises close rates on big tickets. But the economics deserve a clear-eyed read. Say you install a $14,000 system on a promotional plan, and say that plan's dealer fee runs six percent. The homeowner sees $14,000; you collect $13,160. That $840 is a marketing cost, and judged as one it is often excellent — a closed job at a slightly thinner margin beats a lost job at full margin every time.
Here is the part that gets missed. The more of your volume moves onto financed plans, the more those fees compress your margin at exactly the moment your volume peaks — and the promotional plans that close best tend to carry the highest fees. A financing program changes the shape of your cash even while it grows your sales, which makes it, quietly, a working-capital consideration too. Plenty of contractors discover this in August.
The problem you are holding decides which one you need
- 1
Jobs are dying at the kitchen table
That is a close-rate problem, and it is a customer-financing problem. Business capital will not fix it — no amount of money in your account changes what the homeowner can afford each month. Set up a financing program through your distributor or a point-of-sale platform, and read the fee schedule before the promotional plans read your margin.
- 2
The phones ring and you cannot answer
A booked-out calendar, empty racks in the warehouse, a hire you keep postponing, a truck down in your best week — that is a cash-timing problem, and it is what working capital exists for. The money goes into the operation and the season repays it.
- 3
Both at once
Common, and fine. The two products sit on different balance sheets — one on your customers', one on yours — so running both is not doubling up. Growing replacement-heavy shops often layer them deliberately: financing to win the ticket, working capital to deliver it.
How an underwriter actually reads an HVAC file
A deposit history showing $18,000 in March and $140,000 in July is not a red flag to a lender who knows this trade — it is the trade. But that is only true when the pattern is declared. A trough you explain is context. A trough we find is a question, and questions cost days.
Repayment on revenue-based working capital is scheduled around how your money actually arrives — a daily, weekly, or monthly cadence built to your revenue cycle — and the total cost is fixed and known before you sign. There is no compounding meter running against you through the quiet months. For a business whose revenue moves with the weather, that is the entire point of the structure.
One more piece of floor wisdom: urgency does not make anyone more fundable. The owners who use capital best arrange it before the season — while recent statements still show a strong stretch and there is time to put the money into stock and hires — not mid-heat-wave, when every dollar is already spoken for and the best technicians are already hired.
When neither product is the answer
If the business loses money in season as well as out of it, borrowing bridges nothing. Capital funds a gap between today and revenue you can name — it does not repair a structural loss, and taking it for that job makes the problem more expensive. And if what you actually need is a new service van or a fleet addition, that is a job for vehicle or equipment financing, where the asset itself is the collateral — not for revenue-based working capital. We would rather say that plainly at the start than watch the wrong tool cost you a season.
Sorting this out is what a funding advisor is for. One person looks at your season, your stock plan, and what your deposits already carry, and tells you what your revenue supports — and sometimes the honest answer is a different product, or not yet. Express Capital lends its own capital directly — more than $250 million funded, with a 4.8 rating across 590 reviews — and the gate is simple: $250,000 or more in yearly revenue, at least a year in business, and a 580+ credit score. Decisions are made in-house, often the same day, with funding in as little as 24 to 48 hours.
Express Capital Funding · Direct lender
See what your revenue supports
We underwrite in-house and fund from our own balance sheet. $250,000+ in yearly revenue, 1+ year in business, and a 580+ credit score is the gate — a decision the same day, funding in as little as 24–48 hours.
4.8★ from 590 reviews · A+ BBB accredited · $250M+ funded
Frequently asked questions
Is HVAC customer financing the same as an HVAC business loan?
No. Customer financing is a loan your homeowner takes out to pay for their system — a third-party lender reviews them and pays you the invoice, minus a dealer fee. A business loan or working capital facility is borrowed by your company, repaid by your company, and used to run the operation.
Can I offer customer financing and still qualify for working capital?
Yes, and many contractors run both. Underwriting reads your deposits as they actually arrive — invoices funded through a financing platform land in your account like any other revenue. What matters is consistency, time in business, and how much of your cash flow is already committed elsewhere.
Does a slow shoulder season hurt my application?
A declared seasonal pattern is normal in this trade and is read as such. State your peak and trough months when you apply so the file is underwritten on its real shape. A soft stretch with a season ahead of it is worth a conversation.
What do HVAC companies actually use working capital for?
Pre-season equipment stock, hiring and training technicians before the rush, marketing ahead of demand, payroll through the shoulder months, and repairs to the vehicles and tools that earn the revenue. A vehicle purchase is a different product — asset financing — and a good advisor will say so.
Keep reading
Published by Express Capital Funding, a direct lender to U.S. small and mid-sized businesses. This article is general information, not financial, legal, or tax advice, and is not an offer or commitment to lend.
← More insights